FICA Tax on a Nebraska Paycheck: Social Security & Medicare
Social Security and Medicare withholding explained for Nebraska workers
What FICA is
FICA stands for the Federal Insurance Contributions Act. It funds Social Security and Medicare.
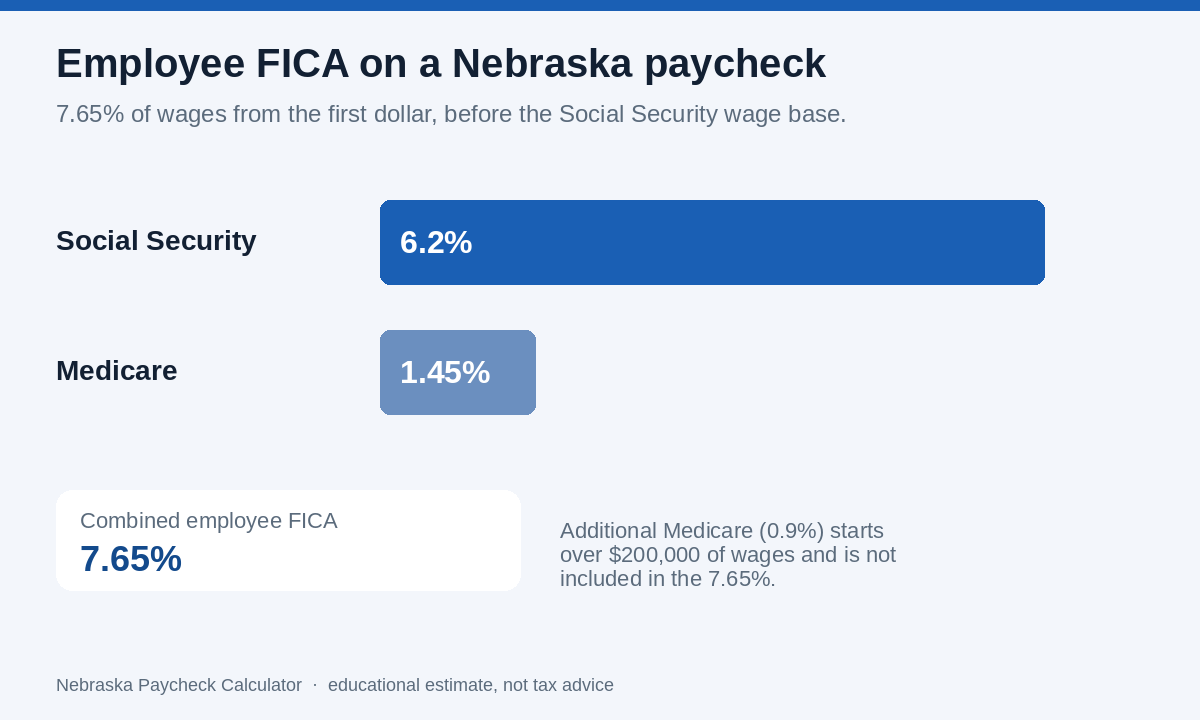
It is a federal tax, so it works the same in Nebraska as anywhere else, but for many Nebraska workers it is actually larger than their state income tax. On a typical paycheck, FICA takes 7.65% of wages from the first dollar earned.
The rates
| Tax | Employee | Employer | Limit |
|---|---|---|---|
| Social Security | 6.2% | 6.2% | Wage base $184,500 (2027) |
| Medicare | 1.45% | 1.45% | No limit |
| Additional Medicare | 0.9% | None | Wages over $200,000 |
Example
A Nebraska worker earning $52,000 a year, paid biweekly, has $2,000 gross per check. Social Security is $124.00 and Medicare is $29.00, for $153.00 of FICA every check, or $3,978 a year.
Nebraska income tax on the same check is often less than that.
| Line | Each biweekly check | Full year |
|---|---|---|
| Gross pay | $2,000 | $52,000 |
| Social Security, 6.2% | $124.00 | $3,224 |
| Medicare, 1.45% | $29.00 | $754 |
| FICA total | $153.00 | $3,978 |
To see FICA alongside federal and Nebraska tax for your own pay, use the Nebraska paycheck calculator.
What reduces FICA wages
Not every pre-tax deduction lowers FICA. Section 125 cafeteria-plan items, such as employer health, dental, and vision premiums, and HSA contributions made through payroll, reduce both income tax and FICA wages.
Traditional 401(k) and 403(b) deferrals reduce income tax wages but not FICA wages, so you still pay Social Security and Medicare on that money.
High earners and the wage base
Once your year-to-date wages pass the Social Security wage base, the 6.2% stops for the rest of the calendar year, and your take-home pay rises. If you have two employers, each withholds separately, so you may over-pay Social Security; you claim the excess back as a credit on your federal return.
The 0.9% Additional Medicare tax starts when one employer pays you over $200,000, regardless of filing status, and is reconciled on Form 8959.
Self-employed Nebraskans
Self-employed people pay both halves as self-employment tax, 15.3% on net earnings, but can deduct half of it. They pay it through quarterly estimated payments rather than paycheck withholding.
Read more about the employer side in Nebraska payroll taxes.
Frequently asked questions
Is FICA refundable?
Generally no. FICA is not refunded at tax time, except for excess Social Security withheld when you have multiple employers, or in limited cases such as certain student and nonresident alien exemptions.
Does Nebraska tax my FICA?
No. FICA is a federal payroll tax.
Nebraska income tax is calculated separately and is not applied on top of FICA amounts.
Do tips count for FICA?
Yes. Reported tips are subject to Social Security and Medicare, and your employer withholds FICA on them from your regular wages.
Will FICA rates change?
The 6.2% and 1.45% rates have been stable for decades. The Social Security wage base rises most years with average wages, so check the new figure each January.